Can You Get Approved for a Toyota with Bad Credit in Lumberton, TX?
Wondering if bad credit will stop you from buying a Toyota in Lumberton, TX? Here's how approval actually works, what to expect, and how to prepare.
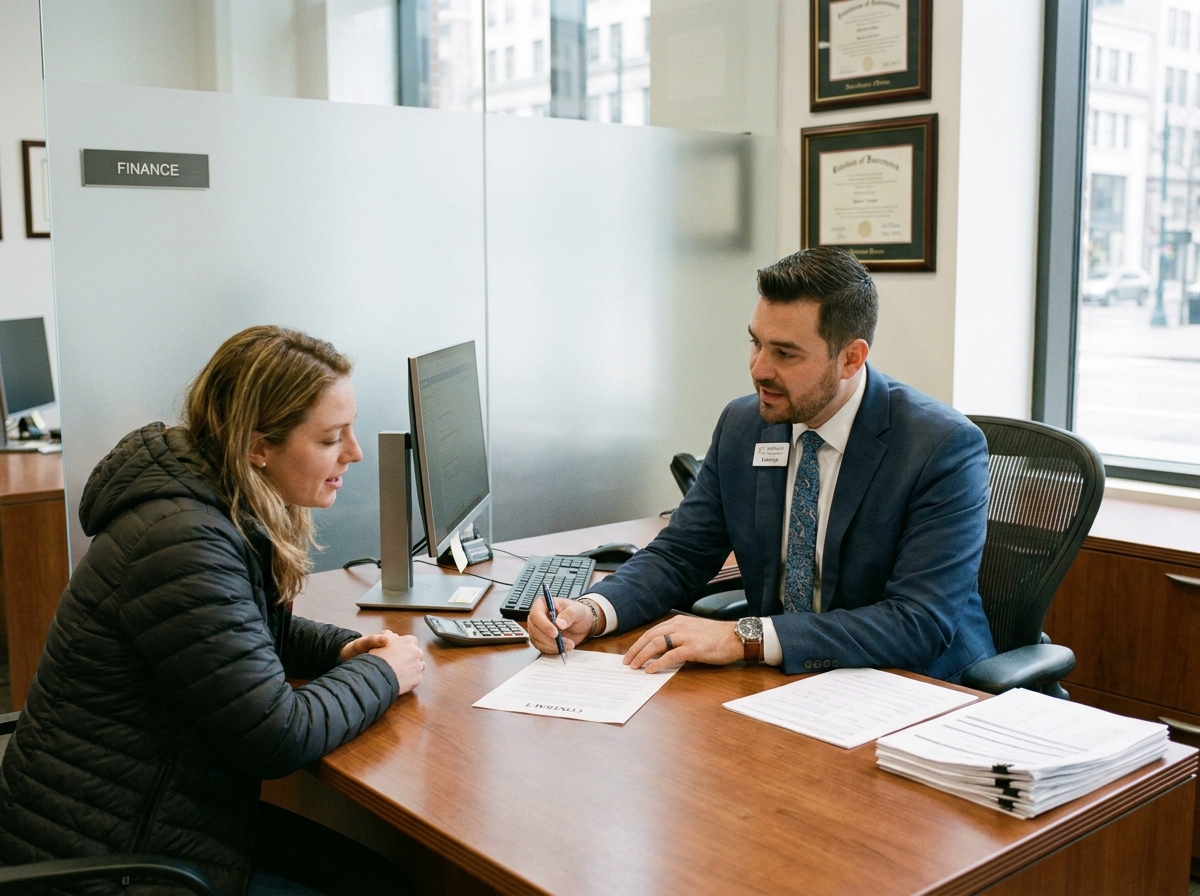
You need a reliable vehicle. Your credit score isn't where you'd like it to be. And you're wondering whether walking into a Toyota dealership in Lumberton is going to end in an approval — or an awkward conversation.
Here's the short answer: yes, you can often get approved for a Toyota with bad credit in Lumberton, TX. But approval depends on more than just your credit score, and understanding how the process works in Texas will save you time, money, and stress.
What "Bad Credit" Actually Means to a Toyota Dealer
Lenders generally treat credit in tiers. Prime borrowers get the lowest rates. Non-prime and subprime borrowers pay more, but they're not automatically shut out.
When you apply for financing at a Toyota dealer in Lumberton, your application typically gets shopped to multiple lenders — captive finance (like Toyota Financial Services), regional banks, credit unions, and specialty subprime lenders. Each has its own risk appetite.
A score in the 500s doesn't disqualify you. It changes the terms.
What lenders look at besides your score
- Verifiable income and how long you've held your job
- Debt-to-income ratio
- Down payment amount
- The vehicle itself (year, mileage, price relative to value)
- Housing stability
- References
Southeast Texas buyers — especially in Hardin County and the surrounding Lumberton area — often work in shift-based industries like petrochemical, timber, and healthcare. Steady pay stubs from a local employer can carry real weight with subprime underwriters, even when the credit report is thin or bruised.
How Texas Law Protects You During the Financing Process
Texas has specific rules that apply to every retail installment sale of a motor vehicle — including yours. This matters because credit-challenged buyers are the most likely to be pressured into terms they don't fully understand.
Under Texas Finance Code Chapter 348, administered by the Office of Consumer Credit Commissioner (OCCC), any retail installment contract for a vehicle must clearly disclose:
- The cash price of the vehicle
- Your down payment (cash and trade-in)
- The unpaid balance of the cash price
- The amount financed
- The finance charge
- The APR
- The total of payments
- The payment schedule
If a number on that contract surprises you, stop and ask. You are entitled to those disclosures in writing before you sign.
Dealers and any person or company that holds or acquires a retail installment contract — including buy-here-pay-here dealers — must obtain a Texas motor vehicle sales finance license from the OCCC. Retail sellers must also use an OCCC-accepted retail installment contract form; outdated forms are not permitted.
Finance charges on Texas motor vehicle installment sales are subject to maximum rate limits under Texas Finance Code Chapter 348. The statute provides two alternative rate structures, and the permissible maximum depends on factors including the vehicle's age and the contract term — there is no single universal ceiling. The OCCC publishes a rate chart for reference. If a rate feels out of line, that's worth a second look.
It's also worth knowing that there is no separate Texas statutory regime triggered solely by a borrower's subprime credit score. All borrowers — prime and subprime alike — are protected by the same contract, rate-limit, and disclosure rules under Chapter 348.
Federal protections on top of Texas rules
The Truth in Lending Act (TILA) requires the same core disclosures federally — APR, finance charge, amount financed, total of payments, and payment schedule — before you sign. The Equal Credit Opportunity Act (ECOA) prohibits credit discrimination and requires a written adverse action notice explaining the principal reasons if you're denied or offered less favorable terms. Keep that notice — it tells you exactly what to work on. The FTC Holder Rule also requires that covered retail installment contracts include a notice preserving your claims and defenses against any subsequent holder of the contract.
What Improves Your Odds Before You Apply
A few practical moves make a real difference for bad-credit buyers in Lumberton:
- Bring a down payment. Even a modest amount changes the math for a subprime lender. It reduces the loan-to-value ratio, which is one of the biggest levers on approval. According to Donalson Toyota's finance center, financing with no down payment is available in most cases — but a down payment can meaningfully improve your terms.
- Gather your documents ahead of time. Recent pay stubs, proof of residence (a utility bill works), a valid Texas driver's license, and proof of insurance. Some subprime lenders also want references.
- Know your trade-in value. A trade-in functions like a down payment. Get a written appraisal before you commit — and remember that in Texas, sales tax on a new vehicle purchase is calculated on the price after your trade-in credit, which is a meaningful savings.
- Be realistic about the vehicle. A certified pre-owned Corolla or Camry is often easier to finance with damaged credit than a loaded new Tundra. The 2027 Toyota Corolla starts at $23,325 MSRP and the 2026 Toyota Camry starts at $29,600 MSRP (per Toyota, as of September 2026) — giving you a sense of the new-vehicle baseline before a used option may bring that figure lower. Match the payment to your budget, not the other way around.
Current Toyota Financing Offers and APR Deals in Lumberton
Toyota Financial Services runs national financing and lease programs that rotate, and those programs generally target well-qualified buyers. If your credit is bruised, you likely won't qualify for the headline advertised rate — but you may still qualify for financing through a secondary lender the dealership works with.
The honest framing: advertised offers are a starting point, not a guarantee. What you actually get depends on your credit profile, the vehicle, and the lender who takes your application. For current program details, visit Donalson Toyota's new vehicle specials page or speak directly with the finance team — a dealer that shops your file to multiple funding sources is usually going to land you a better outcome than a single-lender shop.
Donalson Toyota's finance team works with a variety of local and national lenders to secure competitive interest rates and payment plans, and most loan terms fall between 48 and 72 months. They can also roll taxes, registration, and fees into the financing deal.
Buy-Here-Pay-Here vs. Franchise Dealer Financing
You'll see Buy-Here-Pay-Here (BHPH) lots throughout Southeast Texas. They finance in-house, often with weekly payments, and they'll approve almost anyone with income.
The tradeoff: higher effective costs, older inventory, and — critically — many BHPH loans don't report to the credit bureaus, which means paying on time doesn't help you rebuild credit.
Franchise Toyota dealers work with traditional lenders that do report to the bureaus. If part of your goal is rebuilding your score while you drive, that reporting matters.
Frequently Asked Questions
What credit score do I need to finance a Toyota in Lumberton?
There's no single cutoff. There's no single cutoff, and lenders vary in their risk appetite — a dealer that works with multiple lenders can tell you where you actually land based on your full credit profile and income. A dealer that works with multiple lenders can tell you where you actually land.
Will applying hurt my credit?
A financing application generates a hard inquiry, which can drop your score a few points temporarily. Multiple auto-loan inquiries within a short shopping window are generally treated as a single inquiry by scoring models, so shopping the same week doesn't compound the impact.
Can a co-signer help?
Yes. A co-signer with strong credit can lower your rate or push a borderline application into approval. The co-signer is legally responsible for the loan if you don't pay.
Do I have a right to cancel after I sign?
Texas does not provide a general "cooling-off period" for vehicle purchases. Once you sign the retail installment contract and take delivery, the deal is generally binding. Read every line before you sign.
What if I'm denied?
You'll receive an adverse action notice under ECOA listing the principal reasons. Use it. Common issues — collections, high utilization, thin file — are all fixable with time and a plan.
Does the dealership have to show me all the loan terms before I sign?
Yes. Under both Texas Finance Code Chapter 348 and the federal Truth in Lending Act, the creditor must provide written disclosures — including APR, finance charge, amount financed, total of payments, and payment schedule — before the contract is consummated. If any figure surprises you at the table, stop and ask for a clear explanation before signing.
Can I complete the Toyota financing process without visiting the dealership in person?
In many cases, yes. Donalson Toyota offers customers the option to complete a vehicle purchase entirely online, including trade-in appraisal, financing, payment adjustment, and home delivery. You can also start the process by submitting a finance application online before setting foot in the store, which can save time regardless of your credit situation.
The Bottom Line for Lumberton Buyers
Bad credit narrows your options. It doesn't erase them. With a realistic budget, some documentation, and a dealership willing to work multiple lenders on your behalf, an approval on a Toyota is often within reach — even from a subprime starting point.
Donalson Toyota holds a 4.7-star rating from 1,110 Google reviews as of June 2026, with customers consistently noting a transparent, pressure-free process.
Drivers in the Lumberton area who want to explore Toyota financing with bruised credit can reach the team at Donalson Toyota's finance center — located at 1396 Texas 327, Silsbee, TX 77656, reachable at (409) 895-3700 — to review current programs, get a trade-in appraisal, and see what terms actually apply to their situation. The conversation is more useful than the guesswork.
This article is general information, not legal or financial advice. Specific terms and consumer protections depend on your contract and current Texas and federal law.
"